
The Central Bank of the UAE (CBUAE) is the federal authority responsible for monetary and financial stability in the United Arab Emirates. Unlike a commercial bank such as Emirates NBD, FAB, or Mashreq, it does not operate mainly as a retail bank where customers open everyday current accounts or apply for personal loans. Its role is to regulate financial institutions, oversee the banking and insurance sectors, manage monetary policy and support a stable financial system.
For people and businesses in Dubai and across the UAE, understanding the CBUAE helps explain how banks are supervised, how financial services are regulated, and where consumer protection responsibilities sit.
What is the Central Bank of the UAE?
The Central Bank of the UAE is a federal public institution with financial and managerial independence. Under the current federal framework, it serves as the supervisory and regulatory authority for the UAE’s banking and insurance sectors. Its responsibilities also extend to financial infrastructure, monetary policy, foreign reserves and consumer protection.
The CBUAE was established in 1980, replacing the UAE Currency Board. Today, its work affects almost every part of the country’s regulated financial system, from licensed banks and finance companies to payment services and money transfers.
Its main objectives include:
- Maintaining monetary and currency stability
- Supporting financial system stability
- Managing the UAE’s official foreign reserves prudently
- Supervising licensed financial institutions
- Protecting consumers of financial services
- Supporting safe and efficient financial market infrastructure
- Developing regulations and standards for the financial sector
What does the Central Bank of the UAE do?
The CBUAE’s responsibilities go well beyond supervising traditional banks. Its work covers monetary policy, financial regulation, supervision, payment systems and wider financial stability.
Monetary policy and currency management
One of its core responsibilities is establishing and implementing monetary policy while maintaining the stability of the national currency. The CBUAE also has responsibility for issuing UAE currency and managing official foreign reserves.
These functions influence the broader financial environment in which UAE banks operate, including liquidity, interest-rate conditions and monetary stability.
Banking and financial regulation
Banks and other financial institutions cannot simply provide regulated financial services in the UAE without the appropriate authorization. The CBUAE establishes regulatory requirements and supervises licensed financial institutions to promote sound and prudent practices.
The current Central Bank Law identifies a wide range of activities that fall within its licensing framework. These include deposit-taking, credit and financing facilities, open finance, currency exchange, money transfers, payment services, stored-value services and retail payments.
Financial stability
The Central Bank monitors risks that could affect the UAE’s wider financial system. Its Financial Stability Department assesses potential vulnerabilities and supports decision-making aimed at maintaining a resilient financial sector.
This matters because problems at an individual institution can sometimes have wider consequences. Strong supervision and risk monitoring help reduce those risks.
What the Law Says About the Central Bank
The Central Bank of the UAE is a federal public institution with its own legal identity and both financial and administrative independence. It is the supervisory and regulatory authority for banking and insurance.
It reports directly to the President of the UAE. The governing instrument is the Federal Decree-Law of 2025 on the Central Bank, the Regulation of Financial Institutions and Activities, and Insurance Business, which succeeds Decretal Federal Law No. 14 of 2018.
| Pillar | What it covers |
| Regulatory development | Regulating and supervising financial services companies operating in the UAE |
| Financial stability | Run by the Financial Stability Department, which analyses risks and vulnerabilities in the financial system and supports the bank’s decisions |
| Reserve management | Managing the UAE’s official foreign exchange reserves |
| Islamic finance | Supervising an industry that exceeds USD 2.44 trillion in assets globally, growing at 11.4% |
Islamic banking is not a niche here. It accounted for 23% of total UAE banking assets in 2022, equivalent to AED 845 billion.
Every Licence the Central Bank Issues
Any firm or individual wanting to carry out a regulated activity has to apply for authorisation. The list below is the full set of licence types.
- Banks, both conventional and Islamic
- Insurance companies
- Finance companies
- Representative offices
- Profession for insurance
- Exchange business
- Stored Value Facilities
- Retail payment services
- Loan-based crowdfunding
- Card scheme
- Large-value payment system
- Retail payment system
- Monetary intermediary
- Open finance
A conventional bank licence covers five categories: local banking for individuals, foreign banking for individuals, local corporate banking, foreign corporate banking and specialised banks. An Islamic bank licence covers the same five, with the added requirement that the services comply with Islamic Shari’a.
Exchange houses run under Exchange Business Regulation No. C 7/2025. That covers buying and selling foreign currency and travellers cheques, executing domestic and international remittances, and wage payment services linked to the Wages Protection System. Finance companies run under Board of Directors Resolution No. 3/2023, dated 23 May 2023.
How does CBUAE supervise banks in Dubai?
Banks operating in Dubai and other parts of the UAE that fall under CBUAE supervision must comply with applicable regulations, standards and supervisory requirements.
The Central Bank uses a risk-based approach to supervision. This means it assesses the risks faced by licensed institutions and monitors areas such as financial soundness, governance, operational risks and customer treatment.
Its supervisory role covers important areas including:
- Banking institutions
- Finance companies
- Payment-related activities
- Money transfer and remittance services
- Insurance and related activities
- Financial market infrastructure
- Consumer protection
The purpose is not simply to punish institutions for violations. Effective supervision is designed to support a stable sector, protect customers and encourage responsible financial practices.
Consumer protection under the Central Bank
For individual customers, one of the most relevant areas of CBUAE regulation is consumer protection.
Licensed financial institutions are required to follow rules concerning transparency, customer treatment, fees, account opening, financial products and the handling of consumer information. The regulatory framework also addresses fraud prevention and protection of customer data.
When opening a bank account, for example, customers should receive information about the requirements and applicable fees. CBUAE consumer protection standards also require financial institutions to use appropriate KYC procedures and disclose relevant conditions to customers.
This gives customers a clearer basis for understanding what they are agreeing to before using a financial product.
Protection of customer data
Data protection is another important area. Licensed financial institutions must have policies and controls for collecting, protecting, using and maintaining the confidentiality of consumer data. They are also expected to maintain secure delivery channels and appropriate controls for digital transactions.
For customers using mobile banking, internet banking or other digital financial services, these requirements are particularly relevant.
Payment systems and digital banking
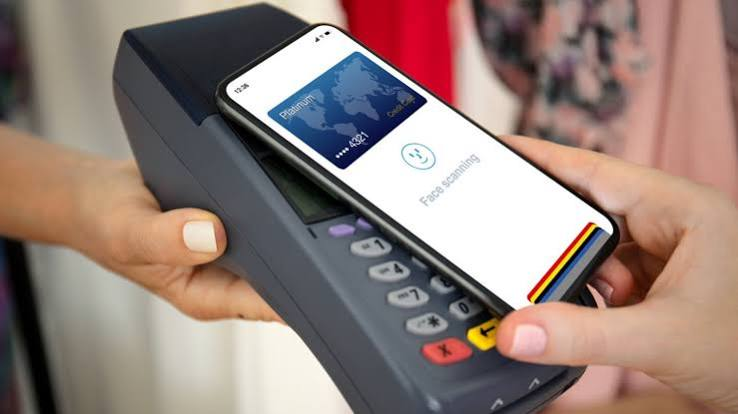
Modern UAE banking depends heavily on electronic payments and digital financial infrastructure. The CBUAE regulates and supervises payment-system activities as part of its wider financial infrastructure responsibilities.
Its framework covers areas including retail payments, digital money, stored-value services and other regulated payment activities. Money transfers and instant money transfer services are also included among activities subject to CBUAE licensing.
This regulatory role is important as UAE customers increasingly use mobile applications, card payments, digital transfers and other cashless services.
Does CBUAE offer bank accounts and loans?
The Central Bank should not be confused with a normal commercial bank.
A customer generally does not visit the CBUAE to open a salary account, obtain a personal loan or apply for a conventional credit card. Those services are normally provided by banks and other licensed financial institutions.
The CBUAE’s role is primarily regulatory and supervisory. It creates the framework within which licensed institutions can provide financial services and monitors their compliance with applicable requirements.
For example:
| CBUAE role | What it means for customers |
| Bank supervision | Banks are subject to regulatory oversight |
| Financial regulation | Financial institutions must follow applicable rules |
| Consumer protection | Customers receive regulatory protections |
| Monetary policy | Supports monetary and financial stability |
| Payment supervision | Helps oversee regulated payment infrastructure |
| Licensing | Certain financial activities require authorization |
| Financial stability | Monitors risks affecting the wider financial system |
| Currency management | Supports stability of the UAE monetary system |
What financial activities require CBUAE licensing?
The current legal framework covers a broad range of regulated activities. These include taking deposits, providing credit and financing, open finance services, currency exchange, money transfers and certain payment-related services.
The framework also includes Shariah-compliant deposits and financing, meaning Islamic financial institutions can fall within the CBUAE’s regulatory framework while operating according to applicable Shariah principles.
This is particularly relevant in the UAE, where conventional and Islamic banking operate alongside one another.
Central Bank and Islamic banking in the UAE
The CBUAE also has a role in regulating Islamic financial institutions. Its regulatory framework recognizes Shariah-compliant deposits and funding facilities as regulated financial activities.
Islamic banks therefore operate within the wider UAE financial regulatory system while following requirements applicable to Islamic finance.
For customers comparing Islamic and conventional banking products, the important point is that both operate within a regulated financial environment, although their product structures and underlying principles can differ.
What should customers check before choosing a UAE bank?
The fact that a financial institution operates in the UAE does not mean every account or financial product will suit every customer.
Before opening an account or taking financing, compare practical details such as:
- Minimum balance requirements
- Monthly or annual fees
- Debit and credit card charges
- Transfer and remittance costs
- Foreign currency conversion charges
- Interest or profit rates
- Early settlement conditions
- Salary transfer requirements
- ATM and branch access
- Mobile banking features
- Customer support channels
- Eligibility requirements
Customers should also check whether the institution and the specific service are appropriately licensed or regulated. CBUAE provides regulatory information and maintains guidance for institutions operating under its supervision.
CBUAE’s role for businesses and companies
The Central Bank’s work is also important for businesses operating in Dubai and elsewhere in the UAE.
Companies depend on regulated financial institutions for corporate accounts, payments, financing, foreign exchange, payroll-related services and international transfers. A stable regulatory environment helps businesses access these services within a structured financial system.
For companies dealing with cross-border payments or regulated financial activities, compliance requirements can be particularly important. Businesses should therefore understand which activities require authorization and which financial institutions are licensed to provide the services they need.
What has changed in the CBUAE regulatory framework?
The UAE’s banking regulatory framework continues to develop as financial services become more digital and interconnected.
The current Central Bank Law, effective from September 2025, sets out updated objectives and powers for the CBUAE, including financial regulation, consumer protection, financial infrastructure and systemic-risk monitoring.
For customers and businesses, this means older information found online should be checked against the latest CBUAE regulations rather than assumed to remain current.
The Dirham, and the Symbol That Changed in 2025
The Central Bank issues the currency. On 27 March 2025 it unveiled a new symbol for the dirham, in both physical and digital form, taking its two horizontal lines across the letter D from the UAE flag.
The same announcement marked the UAE as the first central bank in the Arab region to join the FX Global Code. For the digital dirham the design encircles the D with the colours of the flag.
| Milestone | Detail |
| Currency Board established | Union Law No. 2 of 1973, replaced by Law No. 10 of 1980 on the Central Bank, Monetary System and Organization of Banking |
| Dirham enters circulation | 19 May 1973, replacing the Bahraini dinar in Abu Dhabi and the Qatar and Dubai riyal elsewhere |
| First banknotes | AED 1, 5, 10, 50 and 100 in 1973, with the AED 1,000 note following three years later |
| Coins | 1, 5, 10, 25 and 50 fils, plus AED 1. The dirham divides into 100 fils |
| New dirham symbol | Unveiled 27 March 2025, alongside the UAE joining the FX Global Code |
| IBAN | Mandatory since 2012 for all electronic payments and receipts inside and outside the UAE, except credit card payments. It follows ISO 13616 and is unique to each account |
Banks are required to tell you your IBAN. You hold a separate one for every account, whether those accounts sit at the same bank or at different ones.
Complaining to the Central Bank, and to Sanadak
The Central Bank runs eServices for filing a banking-related complaint and for whistleblowing. It does not act as your first port of call, though.
Complain to your own bank first and keep the date they received it. If 30 calendar days pass without a resolution, take it to Sanadak, the independent ombudsman unit created under the Central Bank, on 800 726 2325.
Sanadak sits in the Emirates Institute of Finance building in Abu Dhabi and opens 8:30am to 3:30pm Monday to Thursday and 8:30am to 11:30am on Friday. It covers licensed banks and insurers.
Frequently Asked Questions
Is the Central Bank of the UAE a commercial bank?
No. CBUAE is the UAE’s central bank and financial regulator. It is different from commercial banks that provide accounts, cards, loans and other everyday banking products directly to customers.
Does CBUAE regulate banks in Dubai?
Yes. Banks and other licensed financial institutions operating under its jurisdiction are subject to CBUAE supervision and regulatory requirements. Its supervisory role covers banking, insurance and payment-system activities.
Can I open a bank account with CBUAE?
No. CBUAE is not an ordinary retail bank. Customers normally open accounts with licensed commercial or Islamic banks operating in the UAE.
Does CBUAE regulate money transfers?
Yes. Currency exchange and money transfer services, including instant money transfer services, are among the financial activities covered by the CBUAE licensing framework.
Does the Central Bank protect banking customers?
Consumer protection is one of the CBUAE’s responsibilities. Its framework includes requirements covering transparency, customer treatment, data protection and other aspects of financial services.
Where can I check official CBUAE regulations?
The CBUAE publishes its legislation, regulations, supervisory guidance and rulebook materials through its official website. Customers and businesses should rely on the latest official material when checking requirements that may change.
Who does the Central Bank of the UAE report to?
The President of the UAE, directly. It is a federal public institution with its own legal identity and financial and administrative independence.
Which law governs the Central Bank of the UAE?
The Federal Decree-Law of 2025 on the Central Bank, the Regulation of Financial Institutions and Activities, and Insurance Business. It succeeds Decretal Federal Law No. 14 of 2018.
What licences does the Central Bank issue?
Banks both conventional and Islamic, insurance companies, finance companies, representative offices, the insurance profession, exchange business, stored value facilities, retail payment services, loan-based crowdfunding, card schemes, large-value and retail payment systems, monetary intermediaries and open finance.
How big is Islamic banking in the UAE?
It accounted for 23% of total UAE banking assets in 2022, equivalent to AED 845 billion. Globally the Islamic finance industry exceeds USD 2.44 trillion in assets.
When did the dirham get a new symbol?
On 27 March 2025. The Central Bank unveiled it for both the physical and digital dirham, and the UAE became the first central bank in the Arab region to join the FX Global Code.
When did IBAN become mandatory in the UAE?
In 2012, for all electronic payments and receipts inside and outside the UAE, except payments made by credit card.
Final thoughts
The Central Bank of the UAE sits at the centre of the country’s regulated financial system. Its responsibilities include monetary policy, currency management, bank supervision, financial stability, payment-system oversight and consumer protection.
For someone in Dubai, the CBUAE is usually not the institution where everyday banking products are purchased. Its importance is behind the scenes: it establishes the regulatory environment in which banks, finance companies, payment providers and other licensed financial institutions operate.
Before choosing a bank or financial product, customers should still compare fees, eligibility, rates, services and conditions rather than assuming that regulatory supervision makes every product equally suitable. For current rules and official requirements, the latest CBUAE publications should be treated as the primary reference.
Official sources
Everything above is compiled from primary sources. Check these directly before you act, because fees and product terms change often and without notice.
- The Central Bank’s mandate and licence types: the UAE government’s official banking page, updated 4 September 2026, which is the source for the Federal Decree-Law of 2025, the four operational pillars and the full licence list.
- The dirham: the official page on the UAE national currency, for the 1973 introduction, the denominations and the new symbol unveiled on 27 March 2025.
- The regulator itself: Central Bank of the UAE, which publishes the CBUAE Rulebook, the licensed entity lists and the complaint and whistleblowing eServices.
- Complaints: Sanadak, the independent ombudsman unit created under the Central Bank for licensed banks and insurers.
- Our method: how we research each bank and what our ratings mean is set out in our editorial policy and ratings methodology.
The banks the CBUAE supervises
See the full list of all 62 banks licensed in the UAE, or start with the largest: Emirates NBD Bank UAE, First Abu Dhabi Bank FAB, ADCB Bank UAE and Mashreq Bank UAE.